Master's Degree ROI: How to Calculate Your Return
Master's degree ROI explained: a step-by-step guide to calculating costs, salary lift, and payback period so you can decide if grad school pays off.
By Jeffrey Hartford
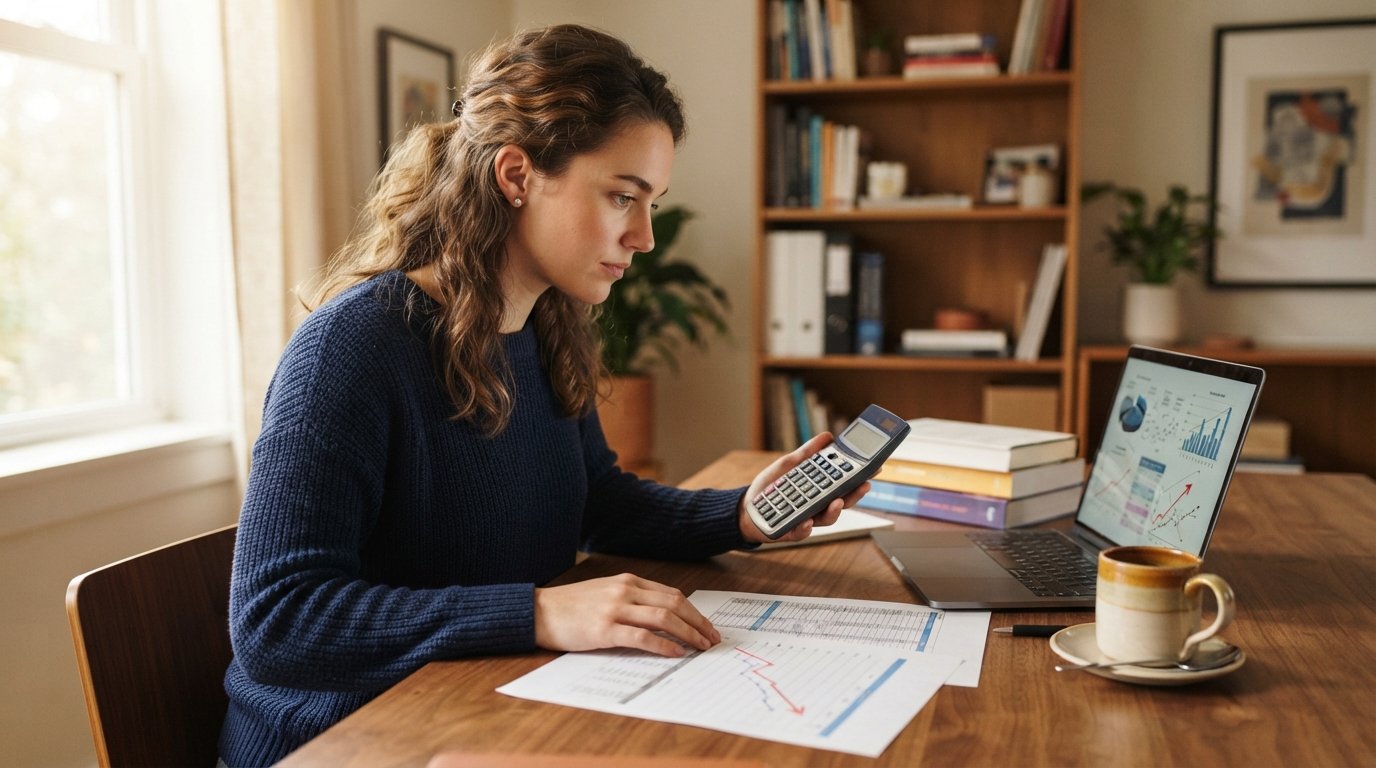
You are staring at a $60,000 tuition bill and wondering if the master's degree is worth it. You are not alone. Every year, thousands of prospective graduate students face the same decision, and the stakes are high. A master's degree can boost your salary, open doors to new industries, and accelerate your career. It can also saddle you with debt that takes decades to repay. The difference between a smart investment and a costly mistake comes down to one thing: return on investment (ROI). This article shows you exactly how to calculate the return on investment for a master's degree, step by step, so you can make an informed choice with confidence.
What ROI Means for a Master's Degree
Return on investment measures the financial payoff of an investment relative to its cost. For a master's degree, ROI compares the total cost of earning the degree against the additional earnings you generate because of it. The formula is straightforward: (Net Gain from Degree / Total Cost of Degree) x 100. But the inputs are where things get complicated. You need to account for tuition, fees, forgone wages while in school, interest on student loans, and the salary increase you expect after graduation. You also need to consider the time horizon: a degree that pays off in five years looks very different from one that takes twenty.
ROI is not just about money, of course. Personal fulfillment, career flexibility, and intellectual growth matter too. But if you are borrowing tens of thousands of dollars, the financial calculation deserves rigorous attention. A 2026 report from the Georgetown University Center on Education and the Workforce found that master's degrees deliver a median ROI of $450,000 over a lifetime, but that figure masks enormous variation. Some programs return over $1 million; others leave graduates worse off than if they had never enrolled. The key is to run the numbers for your specific situation, not rely on averages.
The Core Formula: A Step-by-Step Guide
Calculating ROI for a master's degree requires you to project costs and benefits over a defined period, typically five to ten years after graduation. Follow these steps to build your own model.
- Estimate total program cost. Add tuition, fees, books, supplies, and any required travel or technology. Include the full program length, not just one year. For a two-year program at $30,000 per year, that is $60,000.
- Calculate forgone earnings. If you leave a job to study full-time, you lose your salary. Multiply your current annual take-home pay by the number of years in school. If you earn $55,000 after taxes and the program takes two years, forgone earnings are $110,000. Part-time students lose less.
- Add financing costs. If you borrow, include interest. A $60,000 loan at 6.5% interest over ten years costs about $21,700 in interest. Use a loan calculator to get precise figures.
- Project your post-degree salary. Research earnings data for graduates of similar programs. Use sources like the Bureau of Labor Statistics, payscale reports, or the program's own employment disclosures. Be conservative: use the 25th percentile, not the average.
- Calculate the annual salary lift. Subtract your pre-degree salary from your projected post-degree salary. If you earned $55,000 and expect $75,000, the lift is $20,000 per year. Adjust for taxes: you only keep about 70-80% of that increase.
- Sum the net gains over your time horizon. Multiply the after-tax annual lift by the number of years you are measuring. For a ten-year horizon with a $15,000 after-tax lift, that is $150,000.
- Compute ROI. Divide total net gains by total costs (tuition + forgone earnings + interest). Multiply by 100 for a percentage. A positive ROI means you recoup your investment; a negative one means you lose money.
This framework gives you a clear, comparable number. But remember: garbage in, garbage out. The accuracy of your ROI depends entirely on the quality of your assumptions, so use conservative estimates and sensitivity analysis (testing different scenarios) to see how robust your result is.
Estimating Tuition, Forgone Earnings, and Financing Costs
Tuition is the most visible cost, but it is often not the largest. For full-time students, forgone earnings can dwarf tuition. Consider a two-year program costing $50,000 per year. Tuition totals $100,000. If you leave a $70,000 job, you lose $140,000 in gross salary over two years. That is a total economic cost of $240,000 before you even account for interest. Part-time or online programs reduce forgone earnings because you keep working, but they may take longer and offer less networking value.
Financing costs are equally important. Federal student loans for graduate school currently carry interest rates around 6-7% (fixed for the life of the loan). Private loans can be higher. If you borrow $80,000 at 7% over ten years, you will repay about $111,000 total, meaning $31,000 in interest. That interest is part of your ROI calculation. Some employers offer tuition reimbursement, which dramatically changes the math. If your employer pays $20,000 per year, your net cost drops and your ROI rises. Always ask about tuition assistance before enrolling.
Comparing Salary Lift by Field
Not all master's degrees are created equal. Salary lift varies enormously by field, and so does ROI. According to 2026 data from the National Association of Colleges and Employers, median starting salaries for master's graduates range from $55,000 in humanities to $110,000 in computer science. But starting salary is only part of the story; growth trajectories matter too. Business, engineering, and healthcare management tend to offer both high starting pay and strong mid-career growth. Education and social work often have lower salaries but may offer loan forgiveness programs that improve ROI.
To get field-specific data, consult the Bureau of Labor Statistics Occupational Outlook Handbook, which provides median pay by occupation. Also check the program's own employment reports: many schools publish graduate salaries by program. For a deeper dive into which fields deliver the strongest financial outcomes, see our guide to master's degrees with the highest salaries. That resource can help you benchmark your expectations against real-world outcomes.
How Employer Tuition Assistance Changes the Math
Employer tuition assistance is a game-changer for ROI. If your employer reimburses all or part of your tuition, your out-of-pocket cost falls, sometimes to zero. Many large companies offer up to $5,250 per year tax-free under IRS Section 127, and some offer far more for job-related degrees. Even a partial reimbursement can turn a marginal ROI into an attractive one. For example, a program with a $60,000 cost and a $15,000 annual salary lift might have a 10-year ROI of 50% without assistance. With $30,000 in employer support, that ROI jumps to over 100%.
When evaluating employer assistance, read the fine print. Some programs require you to stay with the company for a certain period or repay the funds if you leave early. Others only cover specific fields or institutions. But if you can secure assistance, it is almost always worth pursuing. Combine employer support with scholarships and assistantships to minimize debt.
Why ROI Varies Widely by Program, Region, and Career Stage
Two people can earn the same master's degree from the same university and experience vastly different ROI. Program format matters: full-time, in-person programs often cost more in forgone earnings but may offer stronger networking and recruiting opportunities. Online programs are cheaper and more flexible but may lack the same career services. Regional labor markets also play a role: a master's in data science might pay $120,000 in San Francisco but $80,000 in a smaller city, while the cost of living differs too. Career stage is another factor: mid-career professionals often see a bigger salary lift because they can leverage existing experience, while early-career students may need more time to realize gains.
Accreditation and program reputation also influence outcomes. Graduates of top-ranked programs tend to earn more, but the cost is higher. The key is to find the program that offers the best net ROI for your goals, not necessarily the highest-ranked one. Use the ROI formula to compare specific programs side by side, and factor in location, format, and support services. If you are unsure where to start, a resource like CollegeDegree.Education can help you explore accredited programs and connect with schools that match your criteria. Their matching tools can save you hours of research and help you focus on programs with strong track records.
Putting It All Together: A Realistic Example
Let's walk through a concrete example. Maria earns $60,000 as a marketing coordinator. She is considering a two-year, full-time MBA program costing $50,000 per year. She will borrow $100,000 at 6% interest over ten years. After graduation, she expects a salary of $85,000, based on the program's employment report. Her forgone earnings are $120,000 (two years at $60,000). Interest on the loan totals about $33,000. Total cost: $253,000. Her annual salary lift is $25,000, or about $18,750 after taxes. Over ten years, that is $187,500. Her net gain is $187,500 - $253,000 = -$65,500. That is a negative ROI. Maria might reconsider, perhaps choosing a part-time program to reduce forgone earnings, or seeking employer assistance. Alternatively, she could target a higher-paying post-MBA role. This example shows why running the numbers is essential.
Now consider James, a software engineer earning $90,000. He enrolls part-time in a $30,000 online master's in computer science while working. His employer reimburses $15,000. He takes two years to finish, with no forgone earnings. His net cost is $15,000 plus minimal interest. After graduation, he earns $105,000, a $15,000 lift, or $11,250 after taxes. Over five years, that is $56,250. His ROI is ($56,250 - $15,000) / $15,000 = 275%. Clearly, James's situation is far more favorable. The lesson: ROI depends heavily on your circumstances, not just the degree itself.
Tools and Resources to Refine Your Calculation
You do not need to be a financial analyst to calculate ROI accurately. Several free tools can help. The Federal Student Aid website offers a loan simulator that shows monthly payments and total interest. The College Scorecard, published by the U.S. Department of Education, provides earnings data for thousands of graduate programs. Payscale and Glassdoor offer salary data by job title and location. And many universities now publish outcome reports that include median salaries and employment rates. Use these resources to ground your assumptions in reality.
For a more personalized approach, consider speaking with a financial advisor or using a spreadsheet to model different scenarios. Test what happens if your salary lift is lower than expected, or if you take longer to graduate. Sensitivity analysis will show you how much margin for error you have. If the ROI remains positive even under pessimistic assumptions, you can proceed with confidence. If not, explore alternatives such as certificates, part-time programs, or waiting until you can secure employer sponsorship.
Beyond the Numbers: Qualitative Factors
ROI is a powerful tool, but it is not the only consideration. A master's degree can provide intangible benefits: expanded professional networks, access to leadership roles, personal satisfaction, and the credibility to switch industries. These factors are hard to quantify but can be worth more than a salary bump. For example, a master's in public health might lead to a lower salary than a tech MBA, but if your goal is to work in global health policy, the degree may be priceless. Similarly, a degree that allows you to work remotely or start your own business may offer lifestyle benefits that outweigh pure financial returns.
When weighing qualitative factors, be honest with yourself about your priorities. Write down what you want from the degree: higher pay, career change, intellectual challenge, or something else. Then assess whether the program delivers those outcomes. If the financial ROI is marginal but the non-financial benefits are strong, the degree may still be a good investment for you. The key is to make the trade-off consciously, not by accident.
Frequently Asked Questions
What is a good ROI for a master's degree?
A good ROI depends on your time horizon and risk tolerance. Generally, an ROI above 100% over ten years is considered strong. That means you recoup your total investment and double it. However, many graduates see much higher returns, especially in fields like engineering, business, and healthcare. Aim for a positive ROI under conservative assumptions.
How do I account for inflation?
For simplicity, you can ignore inflation if you use nominal dollars consistently. But for more accuracy, discount future cash flows to present value. Use a discount rate equal to your expected investment return (e.g., 5-7%). Most people find that discounting reduces the ROI slightly but does not change the overall conclusion.
Should I include living expenses in the calculation?
Only if they differ from what you would spend otherwise. If you move to a new city for school, your living costs may increase. Include the incremental difference, not total living expenses. If you would have the same living costs whether in school or working, exclude them.
What if my employer offers tuition reimbursement?
Subtract the reimbursement amount from your total costs. This will improve your ROI. Be sure to check whether the reimbursement is taxable and whether there are any strings attached, such as a commitment to stay with the company.
Can I calculate ROI for a part-time program?
Yes. The formula is the same, but forgone earnings are usually lower or zero because you continue working. Part-time programs often have higher ROI for that reason, though they take longer to complete.
The decision to pursue a master's degree is one of the most consequential financial choices you will make. By calculating the return on investment, you move from guesswork to strategy. Use the steps outlined here, gather reliable data, and run your own numbers. Whether you choose to enroll or not, you will know that your decision is grounded in evidence, not hope. And that is the best investment you can make in your future.