College Funding Options for Adult Learners Returning to School
Explore college funding options for adult learners returning to school, from FAFSA and employer aid to scholarships. Call (877)-218-7081 for guidance.
By Aubrey Hayes
Going back to college as an adult is one of the most consequential investments you can make in yourself. It can unlock a promotion, a career change, or a higher salary ceiling. But the sticker price can feel overwhelming, especially when you are balancing a mortgage, childcare, or a full-time job. The good news is that adult learners have access to a wider range of funding sources than most people realize, including some that traditional-age students cannot use. The key is knowing where to look and how to combine them strategically.
Unlike teenagers heading off to dorm life, you are likely an independent student in the eyes of the federal government. That status alone opens doors to larger federal loans and grants. You may also qualify for employer benefits, tax breaks, and scholarships designed specifically for people who took a break from education. This guide walks through the most effective college funding options for adult learners returning to school, with practical steps for each one.
Start With the FAFSA: Your Gateway to Federal Aid
The Free Application for Federal Student Aid (FAFSA) is the single most important form you will fill out. It determines your eligibility for Pell Grants, federal student loans, work-study, and many state and institutional aid programs. As an adult learner, you are almost certainly considered an independent student, which means your parents' income is not counted. That typically translates into a higher Expected Family Contribution (EFC) calculation in your favor, making you eligible for more need-based aid.
Many adult students assume they earn too much to qualify for anything. That assumption is often wrong. The FAFSA uses a formula that considers household size, number of family members in college, and other factors, not just raw income. Even if you do not receive a Pell Grant, filling out the FAFSA is required for federal loans, which carry lower interest rates and more flexible repayment plans than most private alternatives.
Here are a few FAFSA tips specifically for adult learners:
- File early. Some aid is awarded on a first-come, first-served basis, so submitting soon after the application opens gives you the best shot.
- Use your most recent tax return. The FAFSA now pulls data directly from the IRS, which simplifies the process.
- Update your information if your circumstances change. If you lose a job, get divorced, or have a significant income drop, you can request a professional judgment review from your school's financial aid office.
- Do not leave any blanks. Incomplete applications are delayed or rejected.
Once your FAFSA is processed, you will receive an aid offer from each school you listed. Compare those offers carefully, looking at the net cost after grants and scholarships, not just the sticker price. For a deeper dive into gift aid, our guide on scholarships and grants for adult learners returning to college covers dozens of programs you can apply for right now.
Employer Tuition Assistance: A Benefit You Might Already Have
Many employers offer tuition assistance as part of their benefits package, but the benefit is often underused because employees do not know it exists or assume it is only for job-related courses. In reality, many companies will reimburse tuition for any accredited degree program, as long as you maintain a certain GPA and remain employed. Some even pay upfront rather than reimbursing you later, which solves the cash-flow problem entirely.
If your employer does not have a formal program, you can still negotiate for tuition support. The best time to ask is during a performance review, when you are discussing your career development, or when you receive a job offer. Frame the request around business value: explain how the degree will make you more effective in your current role or prepare you for a leadership position the company needs to fill. Be specific about the amount you are requesting and offer to sign a retention agreement if that helps ease concerns.
Even if your employer only covers part of the cost, every dollar counts. Combine employer assistance with federal aid and scholarships to reduce your out-of-pocket expenses. Keep in mind that employer tuition assistance above a certain threshold may be taxable, so check current IRS rules.
Scholarships and Grants Designed for Adult Learners
Scholarships and grants are the best kind of funding because they do not need to be repaid. While many scholarships target high school seniors, a growing number are specifically for adult learners, working parents, veterans, and career changers. These programs often consider life experience, community involvement, and professional goals rather than just academic merit.
You can find these opportunities through several channels. Professional associations in your field frequently offer scholarships for members pursuing advanced degrees. Community organizations, labor unions, and religious groups may also have funds set aside. Additionally, many colleges and universities have dedicated scholarships for returning adult students, so ask the admissions office directly. Do not overlook small awards; a $500 scholarship here and a $1,000 grant there can add up quickly.
When applying, tailor each essay to the specific scholarship. Committees want to see that you have thought carefully about your goals and how the award will help you achieve them. If you are unsure where to start, use a scholarship search engine and set up alerts for new opportunities.
Tax Credits and Deductions for Continuing Education
The IRS offers several tax breaks that can significantly offset the cost of going back to school. The most valuable is the American Opportunity Tax Credit (AOTC), which is worth up to $2,500 per year for the first four years of undergraduate study. It is partially refundable, meaning you could receive a refund even if you owe no tax. The Lifetime Learning Credit (LLC) is another option, worth up to $2,000 per year, and it has no limit on the number of years you can claim it. It is available for both undergraduate and graduate courses, including non-degree classes to acquire or improve job skills.
In addition to credits, you may be able to deduct student loan interest, and certain work-related education expenses may be deductible if they maintain or improve skills required in your current job. Keep meticulous records of your tuition payments, fees, and required books and supplies. Your school will send you a Form 1098-T, which you will need when filing your taxes. If you are unsure which credit or deduction you qualify for, consult a tax professional, because the rules can be complex and the savings are substantial.
One more strategy: coordinate your tax credits with your financial aid. If you receive a grant that is designated for tuition, it may reduce the expenses you can claim for a tax credit. Plan ahead with your accountant to maximize both.
Federal Student Loans and Repayment Plans
Federal student loans are a reliable funding source for adult learners, but they should be used thoughtfully. Direct Subsidized Loans are available to undergraduates with financial need, and the government pays the interest while you are in school. Direct Unsubsidized Loans are available to all students regardless of need, but interest accrues immediately. Graduate students can borrow through the Grad PLUS program. The key advantage of federal loans is their flexible repayment options, including income-driven repayment plans that cap your monthly payment at a percentage of your discretionary income and forgive the remaining balance after 20 or 25 years.
Before borrowing, estimate your future earnings and compare them to your projected debt. A good rule of thumb is to keep total student loan debt below your expected first-year salary after graduation. If you are considering a graduate degree, research the earning potential of your intended career to ensure the investment makes sense. CollegeDegree.Education offers a matching service for accredited programs that can help you compare options and estimate costs.
If you already have federal loans from a previous stint in college, going back to school may qualify you for an in-school deferment, which pauses payments while you are enrolled at least half-time. Just be aware that interest may continue to accrue on unsubsidized loans.
Combining Funding Sources for Maximum Impact
Rarely will a single source cover your entire college bill. The most successful adult learners stack multiple types of aid, creating a patchwork that reduces out-of-pocket costs. For example, you might use a Pell Grant to cover part of tuition, an employer reimbursement for another portion, and a federal student loan for the remainder. Then, when tax season arrives, you claim the American Opportunity Tax Credit to recoup some of what you spent.
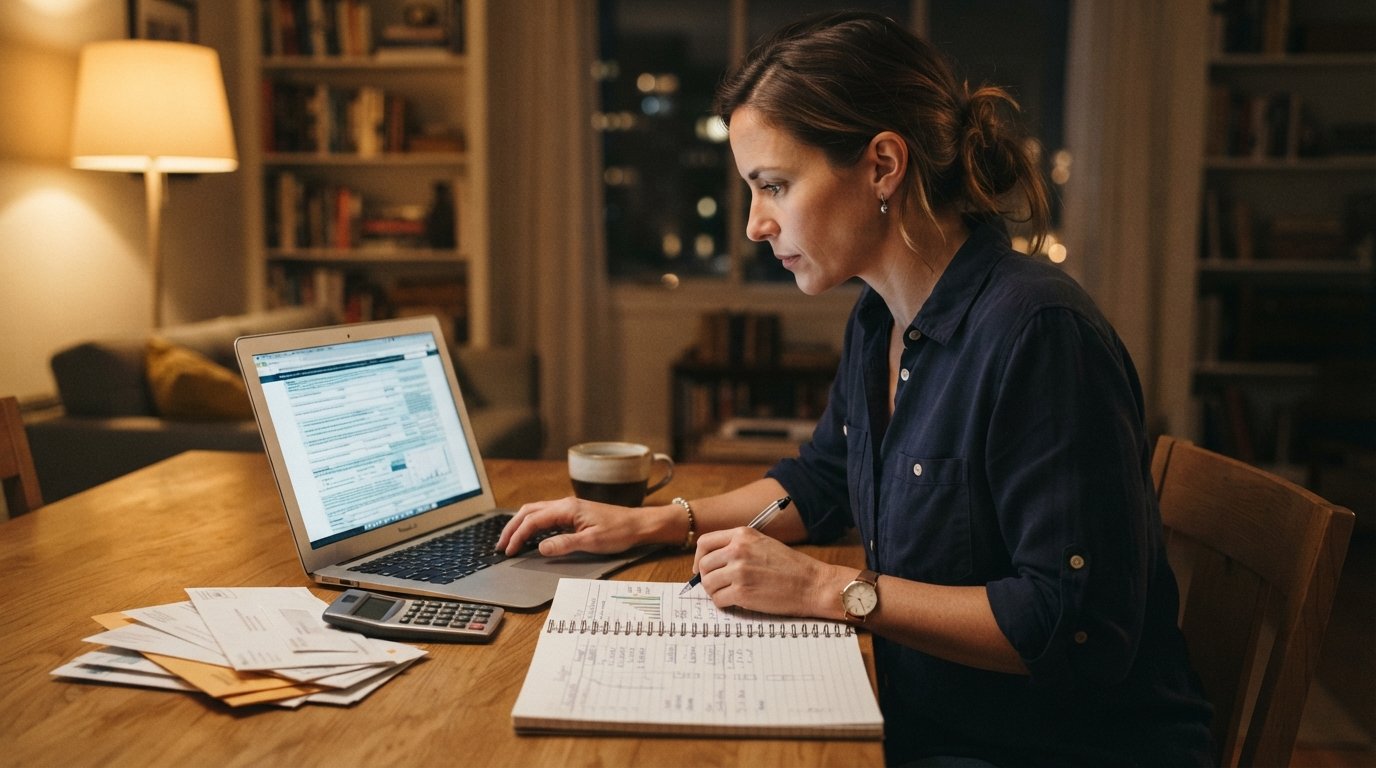
To manage this effectively, create a funding spreadsheet that lists each source, the amount, and any conditions (such as maintaining a certain GPA or staying with your employer for a set period). Review it each semester and adjust as needed. Also, remember to reapply for FAFSA every year, because your eligibility can change based on income fluctuations or changes in the number of family members in college. By staying organized and proactive, you can minimize debt and make your return to school a financially sound decision.
Finally, do not overlook the value of choosing an accredited, affordable program. The school you attend and the program you choose can dramatically affect your total cost and your eventual return on investment. Use resources like CollegeDegrees.School's program search to compare tuition, format, and career outcomes before you commit. With the right combination of funding and a well-chosen program, your degree can pay for itself many times over.